


Latest news

ESG reporting has become a new challenge for CFOs, but SOX compliance experience can provide valuable lessons. This article proposes three key lessons: view reporting as an opportunity beyond compliance, accept imperfect initial data, and stay ahead of exponential change with a digital-first mindset.
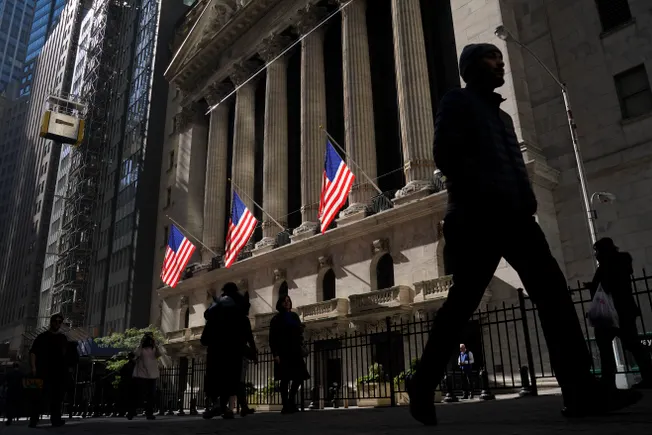
The U.S. Securities and Exchange Commission (SEC) announced that Intercontinental Exchange (ICE) agreed to pay a $10 million fine to settle charges that it caused nine wholly-owned subsidiaries, including the New York Stock Exchange, to violate cybersecurity reporting rules. The issue stemmed from April 2021, when ICE personnel failed to report a cyber intrusion to the SEC within 24 hours, instead taking four days to assess before internally determining the impact was minor. SEC Enforcement Director Gurbir S. Grewal emphasized that for critical market intermediaries, "every second counts" in cybersecurity incidents, and "four days can be an eternity." ICE responded that the incident was an unsuccessful cyber access attempt three years ago with zero impact on market operations, and the dispute centered on the reporting timeline. Two SEC commissioners, Hester Peirce and Mark Uyeda, criticized the fine as an "overreaction."

The latest global survey by the Association of Chartered Certified Accountants (ACCA) shows that 48% of SMEs believe that over the past decade, peers have been more willing to distort financial statements to conceal corrupt practices such as fraud; about three-fifths of businesses believe that peers face bribery risks, and resisting such practices may harm trade opportunities. The United States scored 69 on Transparency International's 2023 Corruption Perceptions Index for the second consecutive year, with progress stalling.
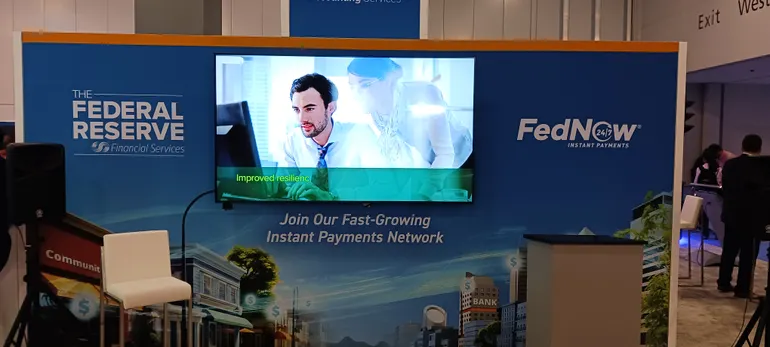
The Federal Reserve launched the FedNow instant payment system in July 2023, but as of this month, only about 700 financial institutions have signed up, whereas Brazil's Pix and India's UPI dominated their domestic transactions within a short period. Through comparative analysis, this article points out that the success of the two countries' systems stems from their design goals that go beyond payments, government-mandated promotion, and merchant participation. In contrast, the United States, due to its abundant existing payment options, prevalent credit card culture, and lack of unified driving force, will find it difficult to replicate similar growth in the short term.

Federal Reserve Chair Jerome Powell said on Tuesday that due to unexpected upside inflation data this year, the Fed may need to keep interest rates at a 23-year high for a longer period, but the probability of another rate hike is 'very small.' He also noted that the policy rate is already restrictive, and the key going forward is to maintain the current rate for longer.

Since it was proposed in the 1970s, zero-based budgeting (ZBB) has always been difficult to popularize due to high implementation costs and insufficient data support. Today, the combination of artificial intelligence and autonomous procurement platforms is solving this historical challenge. The author of this article, Seth Catalli (Chief Revenue Officer of Globality), points out that AI can analyze and memorize spending data at scale, greatly reducing the time and resource requirements for item-by-item justification; at the same time, autonomous procurement platforms, by continuously analyzing indirect spending patterns, provide the data and process foundation for the routine operation of ZBB. This technological evolution not only turns ZBB from an ideal into reality, but also returns to its founders' original intention of "allocating funds based on current strategic intent."

The PCAOB on Monday adopted an updated 'foundational' audit standard, shortening the deadline for final file archiving after audit completion from 45 days to 14 days. The new standard consolidates multiple rules, emphasizing professional skepticism, independence, competence, and judgment, and requires SEC approval, taking effect for fiscal years beginning on or after December 15, 2024. Large audit firms must comply after December 15, 2024, while smaller firms may defer for one year.

The Financial Accounting Standards Board (FASB) this week made an initial decision to provide several workarounds for the compliance difficulties that may arise from its proposed expense classification disclosure rules. The new rules (Subtopic 220-40) would require public companies to disclose more information on expense categories such as inventory, employee compensation, and depreciation. The two-tier disaggregation method, previously a concern for the manufacturing industry, has been proposed to be changed to a single-tier disaggregation method to reduce compliance complexity. KPMG audit partner Valerie Boissou reminded that companies may only have a few years to complete system and process upgrades and need to proactively address investor inquiries about the new information.

Global insurance brokerage and consulting firm WTW said on Tuesday that nearly two-thirds (58%) of companies in the S&P 1500 have incorporated ESG into CEO performance metrics, compared to just 23% in 2019. Despite legal and political pressures, the link between climate goals and executive incentive plans has strengthened notably, but DEI-related metrics have diverged due to legal risks.

A report jointly released by the American Institute of Certified Public Accountants (AICPA) and CPA.com states that generative artificial intelligence (Gen AI) will impact the accounting profession as significantly as the internet or smartphones, but with faster adoption and easier use. This technology is expected to help small accounting firms compete with larger peers by improving efficiency, optimizing data analysis, and mitigating staffing shortages. The report also lists nine types of tasks that financial executives consider most suitable for AI, cites insights from several industry professionals, and reminds readers of data security and ethical risks.